
You have multiple education loans that you are paying, and it is hard to manage. If you have different due dates, interest rates, and balances, your debt can easily get away from you. For those with multiple private student loans, refinancing into one new loan may be a way to simplify payment.
But consolidation is not always cut-your-costs. Evaluate existing debt vs. new offer.
What is Private Loan Consolidation?
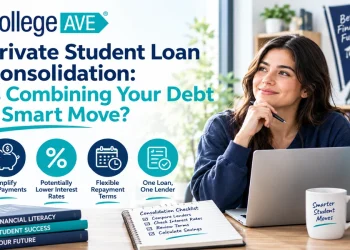
The private loan consolidation typically refers to refinancing several current loans into one new private loan. The old balances are paid off by your new lender which means you will only have one monthly payment to make.
You may be offered a different interest rate or repayment term based on your credit history and income. It also makes it easier to budget, as with one payment.
That said, approval and loan terms vary by lender. Instead, perhaps extending the payback period rather than lowering your interest rate gives you a lower monthly payment.
When Should You Consider Consolidation?
If you are considering consolidating loans, it may be worth doing so if:
- You want to have just one payment each month, instead of several.
- Since your original borrowing, you have a better credit rating or more income.
- You want to see if you can get someone to give you a lower interest rate than what you’re already paying.
- Your monthly repayment period needs to be more in line with your budget.
Check how much you would pay back in total before applying. An extended term would raise the total interest paid over the life of the loan, even if your monthly payments go down.
How to Compare Your Options?
Do you research on the private student loans consolidation options available with multiple lenders before zeroing in on the offer? Check APR, fees, repayment period, and what happens if you miss a payment.
If the new loan has a fixed or variable interest rate, a fixed rate is constant, while a variable rate can change as time goes.
Also, read the fine print. Be sure to learn whether the lender will provide relief and if any fees are charged with the new loan.
Be careful of moving federal student loans into a private loan if you have those, too. Federal loans have less overall flexible repayment options compared to federal student loans, meaning that you may lose access to certain repayment plans and potential forgiveness benefits.
Make Your Next Payment Count
Your repayment plan will become literally manageable when you decide to set it according to your finances, further making the private student loans friendlier. However, debt consolidation works only if the fresh conditions fit your circumstances.
Input your existing balances, shop around for various offers, and the total cost before you commit to anything. With a little diligence, you can make payments without snagging yourself a debt problem that costs you even more.